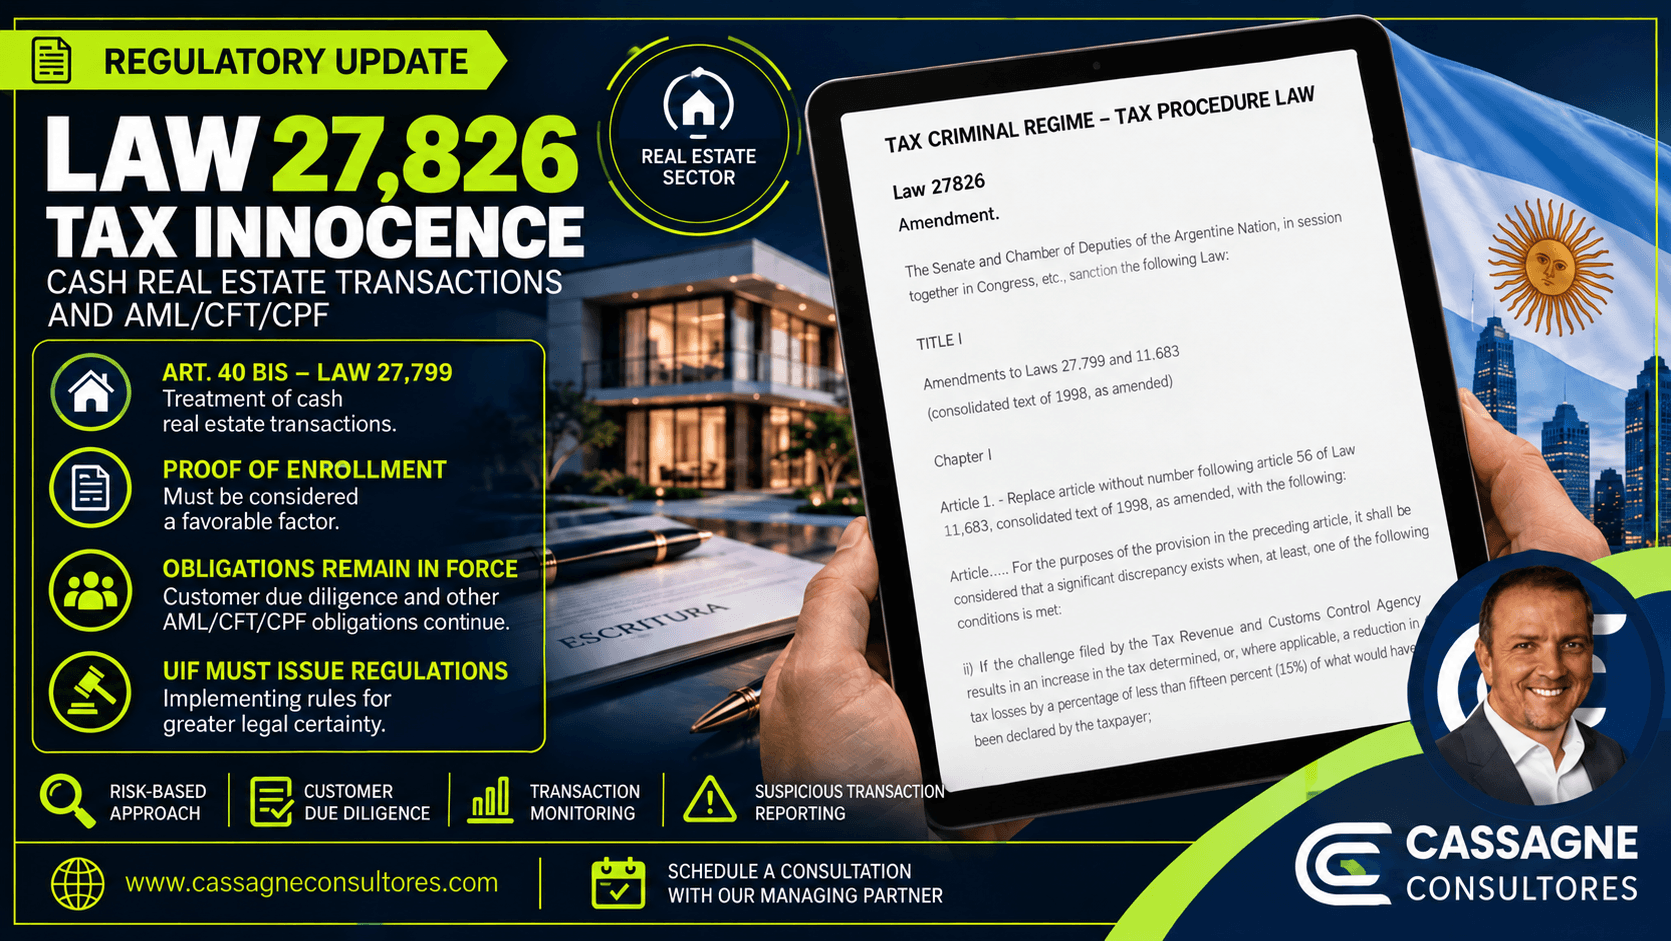
? Today, 9 October 2026, Law No. 27,826 was published, adding Article 40 bis to Tax Innocence Law No. 27,799.
? WHAT DOES THE NEW LAW PROVIDE?
? It expressly addresses cash payments made upon the execution of public deeds relating to rights in rem over real property, establishing specific treatment regarding the requirement to channel funds through the formal financial system.
? It requires Reporting Entities to consider proof of enrollment in the Simplified Tax Return Regime as a favorable factor for identifying and monitoring transactions.
? It clarifies that this does NOT exempt them from complying with AML/CFT/CPF obligations, including Customer Due Diligence.
? WHAT ACTUALLY CHANGES?
The joint UIF?BCRA statement of 18 February 2026 already recognized enrollment in the regime as a factor to be considered under a Risk-Based Approach (RBA).
Therefore, in AML/CFT/CPF terms, the law does not substantially alter the existing preventive approach: enrollment is a favorable factor, but does not automatically establish the source of funds.
?? WHAT IS THE MOST IMPORTANT DEVELOPMENT?
The law expressly requires the UIF to issue implementing regulations.
This should provide greater legal certainty regarding the information and documentation to be requested when a client seeks to substantiate the source of cash used in a real estate transaction through enrollment in the regime.
??? Currently, in the absence of specific criteria, each Reporting Entity must determine, under its own responsibility, what documentation it considers sufficient, with the risk of requesting too much or being challenged by the UIF for requesting too little.
Clear regulations would help reduce this uncertainty, reconciling the objectives of the Tax Innocence Law with AML/CFT/CPF obligations.
? Learn about our services: https://lnkd.in/dRDCs42Q
? Schedule a consultation with our Managing Partner: https://lnkd.in/dvikcFJX